
Intuit Credit Karma
Credit Karma, LLC · Finance
- Rating
- 4.7
- Downloads
- 50.00M
- Content Rating
- Everyone
Intuit Credit Karma - Description
- App Name
- Intuit Credit Karma
- Package Name
- com.creditkarma.mobile
- Developer
- Credit Karma, LLC
- Category
- Finance
- Last Updated
- Feb 28, 2013
- Version
- 26.30
Intuit Credit Karma - Screenshots
Analysis by TrendiApps
When I first open a personal finance app, I want to know what it can help me do today, not just what it might offer someday. Credit Karma is most useful as a place to check credit information, follow changes and get a clearer sense of what may be affecting a score. It is a free finance app from Credit Karma, LLC, and its broad audience—more than 50 million installs and a 4.7 average from around 3.2 million ratings—suggests that many people find this kind of quick access worthwhile. I would approach it as a practical guide, though, rather than a complete financial plan or a substitute for checking details with a lender.
What to expect from a credit-focused app
The first thing to understand is that a credit score is a snapshot, not a verdict on your overall finances. Credit Karma can make credit information easier to follow, but it cannot tell you by itself whether a purchase fits your budget, whether a loan is affordable, or whether a particular lender will approve you. I find that distinction reassuring: the app is better at helping me ask sharper questions than at making decisions for me.
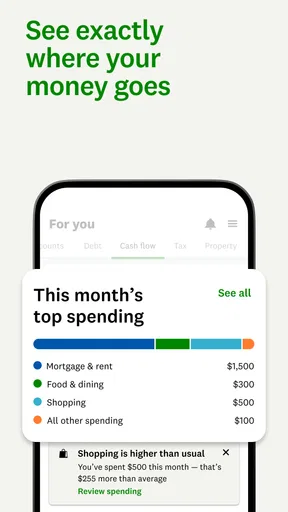
That focus sets it apart from the alternatives people often use. A bank app is usually the natural place to review balances and transactions, while a budgeting tool is better suited to categorizing spending and planning monthly cash flow. Credit Karma’s appeal is the credit-health view: it can help connect report changes and score factors with the choices you make. If you mainly need a spending plan or a single place to view every account balance, I would start with a tool built around those jobs instead.
Make the first setup deliberate
After installing it, take a moment to make sure the account details you enter are accurate and consistent. Credit information depends on matching your identity to the right records, so rushing through setup or guessing at a detail can turn an otherwise simple start into a verification detour. I would use a private moment, choose a password I do not reuse elsewhere, and read each prompt before moving on. Because this is sensitive financial information, I would also avoid signing in on a shared device and would review the app’s available security options rather than assuming the default setup is enough.
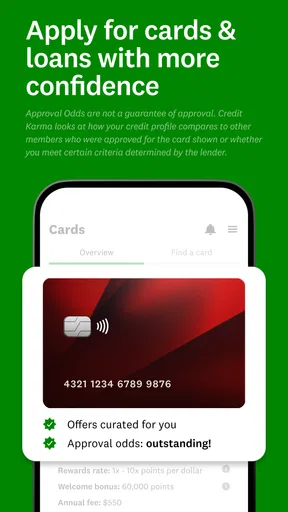
Once you reach the main view, resist the urge to treat every card or recommendation as an instruction. First look for the core credit information and any reported changes; then open the explanation behind a score factor that you do not understand. This order keeps the experience focused. It also helps separate information about your credit profile from offers that may appear alongside it, which is useful when the app is both a monitoring tool and a place to discover financial products.
Your first useful action: investigate one change
A good first session does not need to involve applying for anything or setting a sweeping financial goal. I would choose one item that seems unfamiliar—perhaps a balance, an account, or a change in the report—and check whether I recognize it. If it looks correct, the explanation can still tell me what to pay attention to next. If it does not look familiar, I would make a note of the details and follow up through the appropriate credit-report or financial institution channel instead of assuming that an in-app alert alone resolves the issue.
For example, imagine you are planning to replace an aging car and have a few minutes before a dealership visit. You could check your credit information beforehand, notice whether anything needs investigating, and use the app’s explanations to prepare questions for a lender. That is a more grounded use than treating the displayed score as a promise of a particular rate or approval. Lenders may rely on different information or scoring approaches, so I would use the app to prepare, then confirm terms directly before making a commitment.
Stories You Might Enjoy
Gallery’s Quiet Advantage: It’s Already Where Your Photos Live
Universal TV Remote Control Gets the Basics Right, but Setup Needs Work
Instagram’s Real Advantage Is Keeping Every Kind of Attention in One Place
Shadow Fight 3 Makes Every Duel a Lesson in Timing
Pizza Ready! Makes the Dinner Rush Feel Good—Until It Doesn’t
AliExpress Makes Curiosity Shopping Worth the Search
Use explanations and recommendations with care
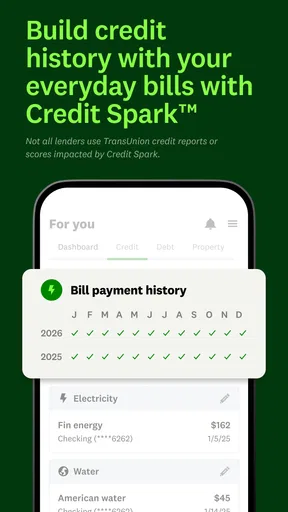
Credit Karma can be helpful when it turns a score into understandable factors rather than leaving you with a number and no context. I would use those explanations to identify a habit worth reviewing, such as how much of an available credit limit is in use or whether payments are being made on time. The practical move is to choose one factor you can influence, make a realistic plan, and check back later—not to change several accounts at once because a screen makes a quick fix look tempting.
Recommendations deserve a separate decision. A card or loan suggestion may be relevant to your profile, but relevance is not the same as suitability, and an offer is not neutral financial advice. Before acting, I would compare the full costs, terms and eligibility requirements with alternatives from my bank or other providers. If I am not actively shopping, I would simply leave the recommendation alone. That keeps the app useful without letting product discovery take over the reason I opened it.
Good fit, poor fit, and everyday trade-offs
I think the app is a good fit for someone who wants a low-friction way to keep an eye on credit, especially if they are new to credit or preparing for a major borrowing decision. It can also suit a person who already checks bank balances elsewhere but wants a separate place to notice credit-related changes. The current version is 26.26, it is rated for Everyone, and it supports devices running Android 10 or later; those details make it straightforward to assess basic compatibility before installing.
I would skip it as a primary tool if what you really want is detailed household budgeting, investment management, or advice tailored to complicated financial circumstances. It is also not ideal for someone who prefers not to place personal financial information in an app or who finds product offers distracting. In those cases, a bank’s own tools, a dedicated budget planner, or a conversation with a qualified financial professional may be a better match for the task.
Understanding Your Financial Snapshot
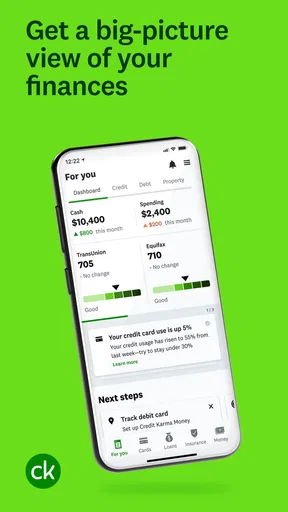
One of the standout features of Credit Karma is its ability to provide a comprehensive view of your financial situation. Once you download the app, which is free, you can easily set up an account. The app offers a detailed breakdown of your credit score, which updates regularly. It's a relief to have all this information in one place, especially if you’re someone who forgets to check different credit bureaus separately.
But it’s not just about the numbers. The app presents insights into factors affecting your score, like credit card usage and payment history. It even suggests personalized recommendations to improve your credit score, which is a helpful touch if you're planning to make big financial decisions soon, like buying a car or applying for a mortgage.
Planning and Goal Setting
In my experience, setting financial goals is crucial, and Credit Karma makes this process straightforward. The app allows you to establish short-term and long-term financial goals. Whether you want to save for a vacation or pay off a student loan, the app helps you track your progress.
An unexpected perk is the app's ability to simulate financial scenarios. You can see how taking out a new loan or increasing your credit card limit might affect your credit score. This feature is empowering because it gives you a clearer picture before making any decisions.
The Benefits of Credit Monitoring
With identity theft being a growing concern, Credit Karma offers free credit monitoring as part of its package. This service alerts you to any significant changes in your credit report, such as a new account opened in your name. For me, this is a huge peace of mind feature. Knowing that the app is keeping an eye on potential fraudulent activities is reassuring.
However, it's important to note that while the app provides excellent monitoring, it might not catch everything immediately. It's always a good idea to remain vigilant and check your credit reports periodically on your own.
Limitations and Trade-offs
While Credit Karma is packed with useful features, it’s not without its limitations. For instance, the app primarily pulls your credit score from TransUnion and Equifax. If your lender uses a different bureau, you might see a slight discrepancy in scores. This isn’t a deal-breaker, but it's something to keep in mind if you're relying solely on the app for credit decisions.
Additionally, the app suggests financial products like loans and credit cards. These recommendations are based on your credit profile, but sometimes they feel more like ads than personalized advice. While they can be helpful, it's essential to do your own research before committing to any financial product.
Who Should Use Credit Karma?
In my opinion, Credit Karma is ideal for anyone looking to get a handle on their financial health. Whether you're new to managing credit or a seasoned pro, the app offers valuable tools and insights. However, if you're someone who prefers using a full-service financial advisor for all your financial decisions, this app might not replace that personalized touch.
On the flip side, if you're a tech-savvy individual who likes having financial data at your fingertips, Credit Karma is a game-changer. The app's user-friendly interface and actionable insights make it easy to incorporate into your daily routine.
Final Thoughts
Overall, my experience with Credit Karma has been positive. It's a powerful tool for monitoring credit and setting financial goals. While it’s not without its quirks and limitations, the benefits it provides far outweigh the drawbacks. If you’re looking for a free, convenient way to keep track of your financial health, I’d recommend giving it a try. Just remember to use it as one of many tools in your financial toolkit, rather than the only one.
As always, the best financial decisions are informed ones, and Credit Karma certainly equips you with the knowledge you need to make those decisions confidently.
Intuit Credit Karma FAQ
Is Intuit Credit Karma free to use?
Yes, Intuit Credit Karma is completely free to use. The app provides users with access to their credit scores, credit reports, and personalized financial recommendations without any cost. It generates revenue by offering personalized product recommendations and financial services, which users can choose to explore or ignore.
How often can I check my credit score with Intuit Credit Karma?
Users can check their credit scores as often as they like with Intuit Credit Karma. The app provides free access to updated credit scores and reports from TransUnion and Equifax on a weekly basis. Regular updates help users monitor their credit health and identify any potential issues early.
Does using Intuit Credit Karma affect my credit score?
No, checking your credit score with Intuit Credit Karma does not affect your credit score. The app performs a 'soft inquiry,' which is different from a 'hard inquiry' that lenders use when you apply for credit. Soft inquiries do not impact credit scores and are not visible to potential lenders.
What security measures does Intuit Credit Karma use to protect my information?
Intuit Credit Karma employs advanced security measures to protect user information, including 128-bit encryption and secure servers. The app adheres to stringent privacy policies, ensuring that user data is kept confidential and secure. Users can trust that their sensitive financial information is handled with utmost care.
Can I dispute errors on my credit report through Intuit Credit Karma?
While Intuit Credit Karma itself does not directly handle disputes, it provides tools and guidance for users to identify and dispute errors on their credit reports. The app offers resources and links to the credit bureaus, enabling users to report inaccuracies and work towards correcting them efficiently.
Intuit Credit Karma Pros and Cons
Pros
- User-friendly interface for easy navigation.
- Provides free credit scores and reports.
- Offers personalized financial advice.
- Monitors credit changes with alerts.
- Integrates well with various financial tools.
Cons
- Ads can be intrusive at times.
- Limited support for international users.
- Requires personal information for setup.
- Some features need internet access.
- Occasional app performance issues.
Ratings From Real Users
4.7
3.21M ratings
- 584%
- 410%
- 33%
- 21%
- 13%


